Automated Credit Control and Late-Payment Charges
Automated credit control gives a telecoms reseller a consistent way to follow up overdue invoices while keeping account-specific decisions visible. The useful work is more than sending reminders: the team needs to recognise a failed collection, a disputed usage charge or an agreed payment date before deciding what happens next.
SAFE Credit Control works from the platform’s invoice ledger and customer record. Statutory interest can form part of a commercial collection policy, but the right to charge it and the practical task of recovering an invoice are separate considerations.
Start With the Outstanding Balance
Before contacting a customer, establish what remains unpaid after payments, credits and allocations. An invoice total alone can overstate the amount due, particularly where a customer has paid part of the bill or a specific charge has been adjusted.
The system rechecks the recorded position before eligible actions proceed. This depends on timely payment recording: a bank transfer that has not yet reached the ledger cannot be recognised as settlement by the workflow.
For a reseller, this matters around regular billing and collection runs, when many account balances can change together.
Build Stages Around a Defined Policy
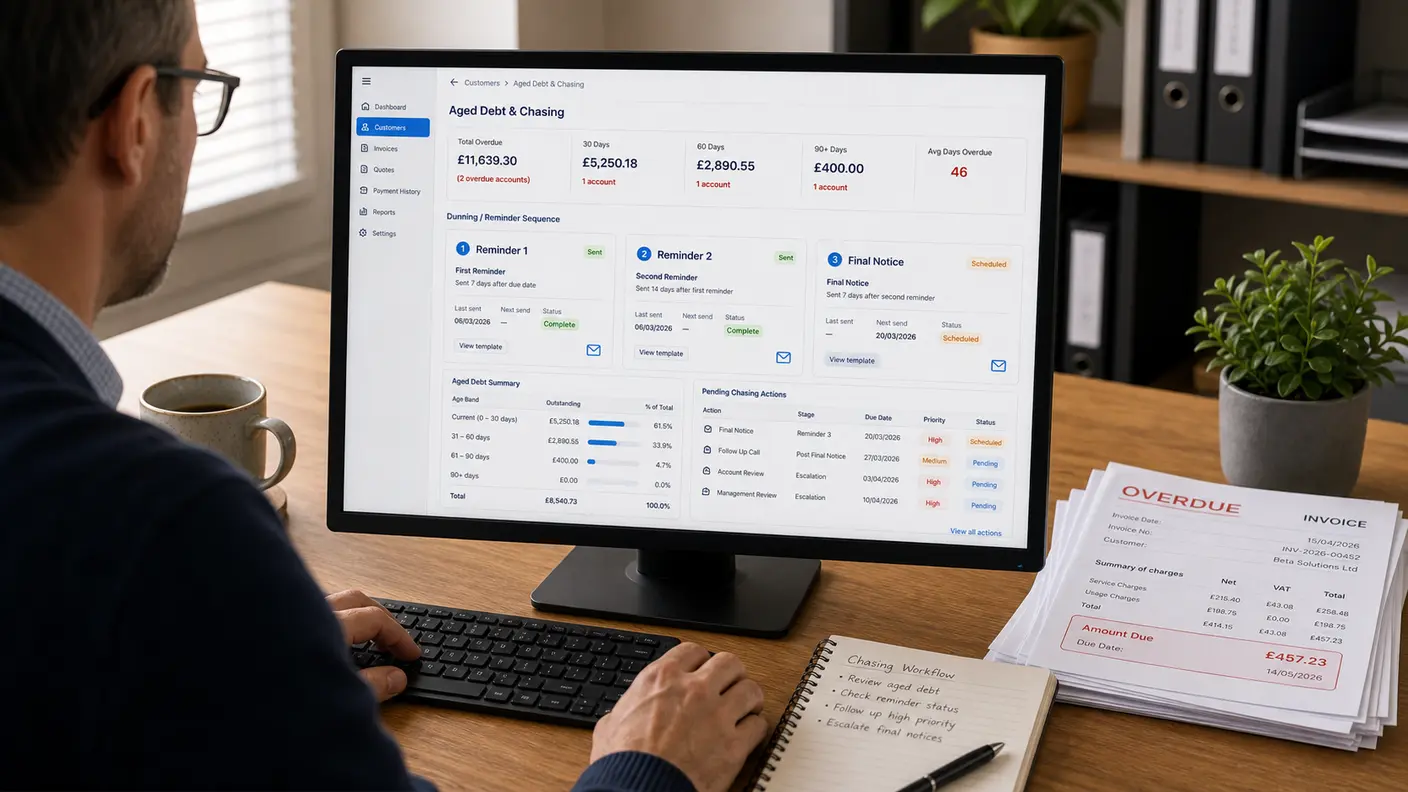
A chase plan sets out when work becomes due and what should happen. Early contact can confirm the outstanding invoice and payment route; a later stage can ask for a response or assign a review task. Use wording and timing appropriate to the customer and the agreement.
Contact stages support automatic sending or creation for approval. In the latter case, the communication waits for an authorised review before dispatch. Manual non-contact steps can bring a person into the process for a call or decision.
A schedule should not make unsupported threats about suspension or recovery action. Those decisions require the applicable contractual, customer-protection and internal approval checks.
Keep Exceptions in the Workflow
A usage dispute should identify the affected invoice, calls or transactions and amount. A payment promise should record the agreed date. Failed collections need their outcome examined before a retry is attempted.
Configured holds and customer classifications can prevent inappropriate contact, charges or restrictions. Review what is protected and why, rather than assuming either that all activity continues or that every issue freezes the entire account.
Where enabled, customers can choose one permitted payment date for their full current collectible balance. Staff can then follow up the promise and check the recorded payment.
Statutory Interest and Recovery Costs
For qualifying commercial debts, statutory interest is generally 8 percentage points above the applicable Bank of England reference rate. A contractual interest provision can change the position. Fixed recovery compensation also depends on the debt amount. GOV.UK explains the interest rules and recovery costs.
The late-payment interest calculator helps estimate a charge using the appropriate inputs. Check eligibility and the reference rate for the relevant period before applying it. Commercial-debt rules should not be applied indiscriminately to residential customers.
Review collection outcomes and customer circumstances when deciding how interest belongs in the policy.
Measure Collections Separately From Balance Reductions
An aged debt report shows where money remains outstanding. To assess collection work, also distinguish cash received from credits, write-offs and other corrections. A smaller debtor balance does not necessarily mean more money reached the bank.
SAFE’s measurements distinguish recorded collections and adjustments, with reporting context for the period covered. A payment received after contact is an observed sequence of events; it does not by itself prove that the contact caused the payment.
A Reseller’s Daily Review
A useful review brings together overdue items, failed or missing collection arrangements, held cases and promises needing attention. Staff can then act from the account context instead of reconstructing it from separate lists.
See the Credit Control product page for the workflow, or the broader credit control process guide for setting policy. Contact us to review a representative collection cycle from your own telecoms business.
Dr Paul Barrass
Founder & Technical Director, Safe Online Billing
Paul founded Safe Online Billing in 2005 and has built telecoms billing software for UK resellers for over 20 years. About the team →